Blog
- Home
- Blog
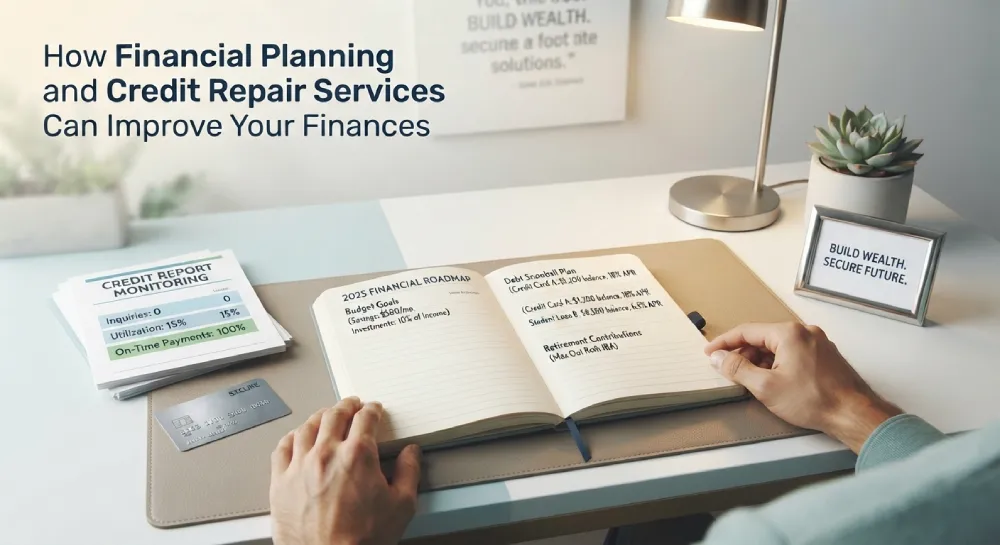
Managing your finances can feel easy until bills start piling up, debt becomes harder to manage, or an unexpected expense throws your budget off track. While you know you need to save more or pay down debt, the challenge is in getting started.
Financial planning and credit repair services can assist in this regard. Financial planning provides you a bit more direction as to what you should be doing with your cash, and credit repair is about finding out credit issues that could be harming your credit profile. They can support you in making better financial decisions and ease your way towards stability.
Financial planning isn't just about how much money you earn. It's about how you manage your income, spending, savings, debt, and future goals.
A well-drafted financial plan can assist you to:
The greatest advantage is clarity. It's much easier to determine what needs to change once you can clearly see your income and expenses.
A bad credit history isn't just for when you are looking to get a loan. Your credit may impact loan terms, interest rates and other financial opportunities, depending on the situation.
Most credit repair companies will look for mistakes, outdated data that does not belong on your credit report and educate consumers on what steps they can take to resolve legitimate errors.
Keep in mind that while negative information may be unpleasant, it is crucial that it not be eliminated because it is incorrect. Avoid anyone who guarantees or promises to raise your credit score quickly.
Revisiting information and correct errors can be a crucial action to take in the event of any mistakes.
See the financial landscape in a broader perspective. Credit is just part of it.
While you may be able to successfully delete an incorrect entry from your credit history, if you continue to fall behind on payments or incurring debt that you don't have the money for, then the financial issue isn't solved.
Financial planning can assist you to break those habits, by providing you with a practical system to manage your money. Meanwhile, having some knowledge of one's credit will help in making more informed borrowing choices, with regards to loans, credit cards, and other types of loans.
These methods can be used together in order to help you concentrate on the immediate issue and the habits you have which have an impact on your finances over time.
Don't have to do it all at once. Make it a gradual process take small steps.
Check your budget. Review your monthly income, bills, debt payments and spending. A good starting point is knowing the numbers.
Take a look at credit reports for unfamiliar accounts, incorrect balances, payment data inaccuracies, and any other errors.
If you have high-cost debt, making a payment on it can lower your interest payments and enable you to pay off other bills or goals.
Build an emergency fund. Even saving a small amount regularly can help when unexpected expenses arise.
Make timely payments paying bills on time is crucial for keeping your credit score good.
Make realistic goals rather than telling yourself you want to be better with money, set specific goals like paying down a debt or a savings target per month.
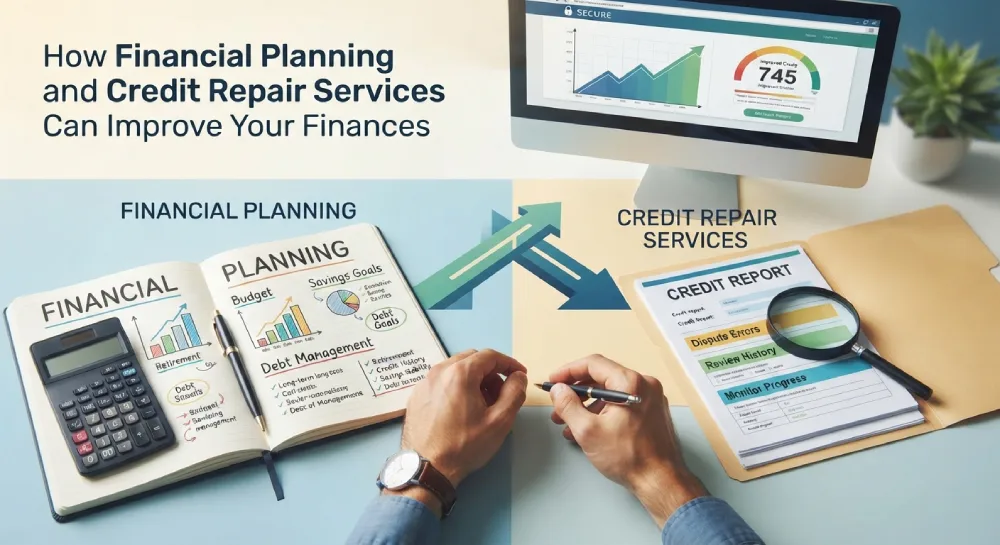
At times, it is possible to handle your finances by yourself. In other circumstances, it may be useful to have professional advice.
A financial professional can be useful if you have complex goals, have a lot of debt, have difficult investments or if creating a manageable financial plan is difficult. Credits or credit related services may also be available to help you better understand your credit reports and options.
When paying for a service, be sure you know what it provides, what the price is, and what to expect.
Financial planning can assist you in organizing your finances and work towards your financial objectives and responsible credit repair efforts can help you solve real issues in your credit reports. The extra time to plan becomes a better financial approach, and you'll have a better base going forward.
Financial planning is the process of organizing your income, expenses, savings, debt, and financial goals so you can make more informed decisions about your money.
Credit repair services may help consumers review credit reports, identify potentially inaccurate information, and understand the process for disputing legitimate errors.
No. Accurate negative information generally cannot be removed simply because it lowers your credit score. Credit repair should focus on legitimate inaccuracies or other appropriate options.
Financial planning can help you understand your spending, manage debt, build savings, prepare for major expenses, and create a realistic path toward your financial goals.
Yes. Reviewing your credit reports can help you notice unfamiliar accounts or inaccurate information and take appropriate action when something does not look right.
Budgeting does not directly change your credit score, but it can help you manage payments, reduce unnecessary debt, and avoid missed payments that could negatively affect your credit history.
It can be useful when your financial situation or goals are complicated. The value depends on your needs, the professional’s qualifications, the services provided, and the fees involved.
There is no universal timeline. Some changes, such as reducing unnecessary spending, can help quickly, while paying down debt and building savings may take much longer.
Start by reviewing your income, expenses, debts, savings, and credit reports. Then choose one or two realistic priorities instead of trying to change everything at once.
Yes. Financial planning can address your overall money management, while responsible credit repair can focus on legitimate credit-report issues. Together, they can support a more complete approach to financial health.
